Decode the Market. Build the Future.Capture the Alpha.

BOOTCAMP DAY
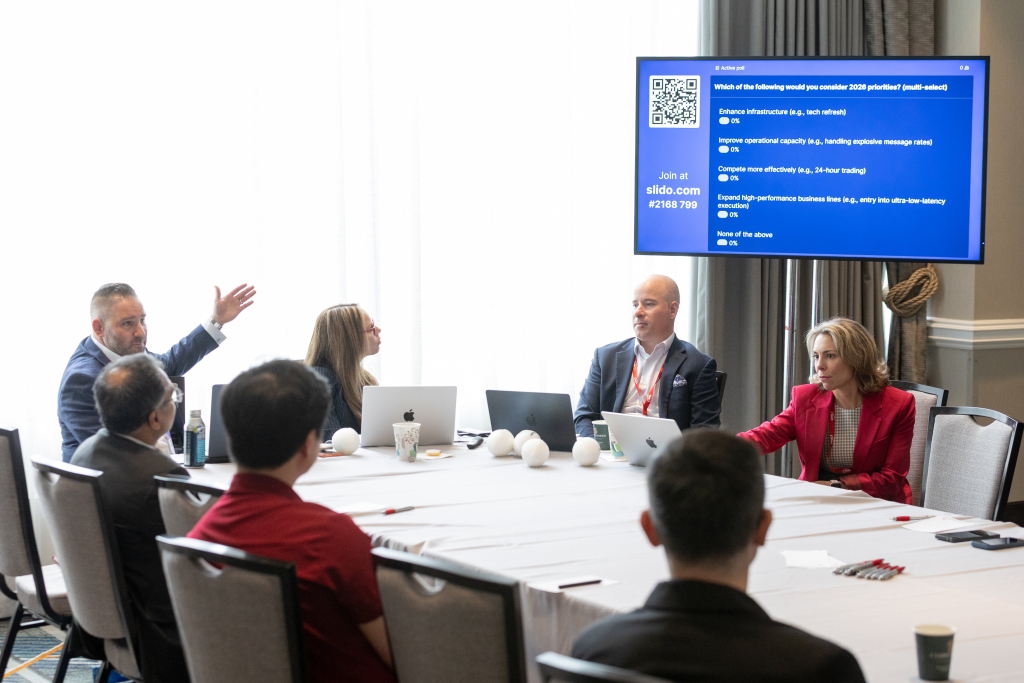
The Future Alpha Bootcamp Day brings together investment teams, quants, risk specialists, engineers and data leaders for a day of technical depth and hands-on learning - not lectures, working sessions. Built to address genuine skills gaps identified by the market, choose from two bootcamps, each led by leading experts and designed to unite teams in deep-dive sessions that build cross-functional fluency and sharpen alpha-ready capabilities.
One day. Two tracks.
These are working rooms, built for practitioners to leave with something they can actually use.

From Hype to Execution: AI in Trading
A working day for analysts, quant researchers, and PMs who want to scale their research with AI, not just experiment. The gap is rarely the model — it's the context you feed it and the control you keep over it. You'll brief AI on a real name and pressure-test its draft against the filings, point it at a whole coverage universe, turn unstructured sources into an event study, and ship a governed tool live. Hands-on throughout, led by AI-trained practitioners.
Session led by:

From Theory to Out-of-sample Results: Quantitative Asset Pricing Research With LLMs
A working day for financial markets researchers who want to go beyond the classical factor model and into where state-of-the-art financial economics is actually heading. From new data sources to new modelling techniques, the gap is rarely the math - it's translating frontier theory and models into out-of-sample results. Hands-on and laptop-based throughout, led by finance academics and practitioners. Attendees leave with artifacts and models from cutting edge academic research.
Session led by:


The day, module by module.
AI in Trading
1.00-3.00pm First Draft, Faster: Single-Name Research from Filings to Note
Building an agent that drafts first-pass notes, earnings previews, and meeting-prep packs. We'll assemble a real name's source set, write the brief, generate a draft, and pressure-test it against the filings to catch what's plausible but wrong. Leave with a reusable briefing template and a verification checklist.
1.00-3.00pm Coverage at Scale: An Agent That Watches Your Universe
Building an agent that watches a coverage list and surfaces what needs attention. We'll set the universe and inputs, define what counts as material versus noise, design the daily briefing and alerts, then add escalation rules for when the triage is trusted versus when a human steps in. Leave with a working monitoring agent and a triage rubric.
3.30-5.00PM Reading the Reaction: Event Studies from Unstructured Sources
Building a workflow that turns unstructured sources into a structured event dataset and measures price reactions. We'll extract and validate events, join them to a price feed, and interpret the result.
3.30-5.00PM From Prototype to Piloted Tool: Shipping and Containing an AI Agent
Taking one of the afternoon's prototypes and deploying it as a real tool on Railway, then adding the governance layer - guardrails, monitoring, and a trigger for pulling the tool if it drifts.
Quantitative Asset Pricing
1.00-3.00pm Modern Asset Pricing/Financial Markets Research - What's Actually Changed
Orientation: How new data and techniques are reshaping model design and feature engineering.
1.00-3.00pm Language in Asset Pricing Models - Textual Analysis, LLMs, & Financial Markets
The flagship technical block, an author-led blueprint of state-of-the-art asset pricing research in a hands-on Jupyter session. We will build complex models with LLM output and have group feedback/Q&A.
1.00-3.00pm Stress-testing Your Work - Overfitting, Robustness & Out-of-sample Discipline
Hands-on experience ensuring the robustness of research results, including tests of overfitting, regime sensitivity, frictions sensitivity, and more.
3.30-5.00PM From Model to Book - Deployment, Decay & Monitoring
How a validated model actually goes live: deployment discipline, detecting signal decay, retraining cadence, and rules-based triggers for pulling a model rather than letting it quietly fail.
3.30-5.00PM Cross-Functional Model Governance Workshop
A closing working session, not a panel: small groups build a model validation/governance checklist for their own shop, tying the day's five artifacts into one through-line.
Two tracks. One day. Places are limited.