March 16 - 17, 2027
| Javits Center, New York
Decode the Market. Build the Future.Capture the Alpha.
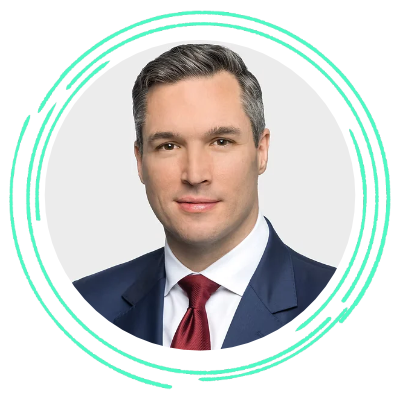
Prof Bryan Kelly
Head of Machine Learning AQR Capital ManagementSkills Accelerator Workshops I Monday March 15
1:00 PM Workshop Two - From Theory to Out-of-sample Results: Quantitative Asset Pricing Research With LLMs
A working day for financial markets researchers who want to go beyond the classical factor model and into where state-of-the-art financial economics is actually heading. From new data sources to new modelling techniques, the gap is rarely the math - it's translating frontier theory and models into out-of-sample results. Hands-on and laptop-based throughout, led by finance academics and practitioners. Attendees leave with artifacts and models from cutting edge academic research.
Across 4 hours, you will explore 5 distinct modules:
Module 1 - Modern Asset Pricing/Financial Markets Research - What's Actually Changed
Orientation: How new data and techniques are reshaping model design and feature engineering.
Module 2 - Language in Asset Pricing Models - Textual Analysis, LLMs, & Financial Markets
The flagship technical block, an author-led blueprint of state-of-the-art asset pricing research in a hands-on Jupyter session. We will build complex models with LLM output and have group feedback/Q&A.
Module 3 - Stress-testing Your Work - Overfitting, Robustness & Out-of-sample Discipline
Hands-on experience ensuring the robustness of research results, including tests of overfitting, regime sensitivity, frictions sensitivity, and more.
Refreshment & Networking Break
Module 4 - From Model to Book - Deployment, Decay & Monitoring
How a validated model actually goes live: deployment discipline, detecting signal decay, retraining cadence, and rules-based triggers for pulling a model rather than letting it quietly fail.
Module 5 - Cross-Functional Model Governance Workshop
A closing working session, not a panel: small groups build a model validation/governance checklist for their own shop, tying the day's five artifacts into one through-line.
Evening Networking & Drinks Reception
Check out the incredible speaker line-up to see who will be joining Bryan.
Download The Latest Agenda